How to File a Roof Insurance Claim in Texas and Get Your Full, Fair Payout
May 21, 2026 · 9 min read · By the LoneRidge Roofing Team
Maximizing a roof insurance payout in Texas does not mean inflating anything. It means claiming everything your policy legitimately owes — no line item missed, no code requirement skipped, no documentation gap an adjuster can trip over — and nothing beyond it. Homeowners leave money on the table through thin documentation, unrecorded code upgrades, and supplements never filed. This guide covers the honest levers that produce a full, fair settlement: evidence, matching, code, supplements done properly, and the Texas deductible law that separates legitimate contractors from fraudulent ones.
Start With Documentation That Leaves Nothing Out
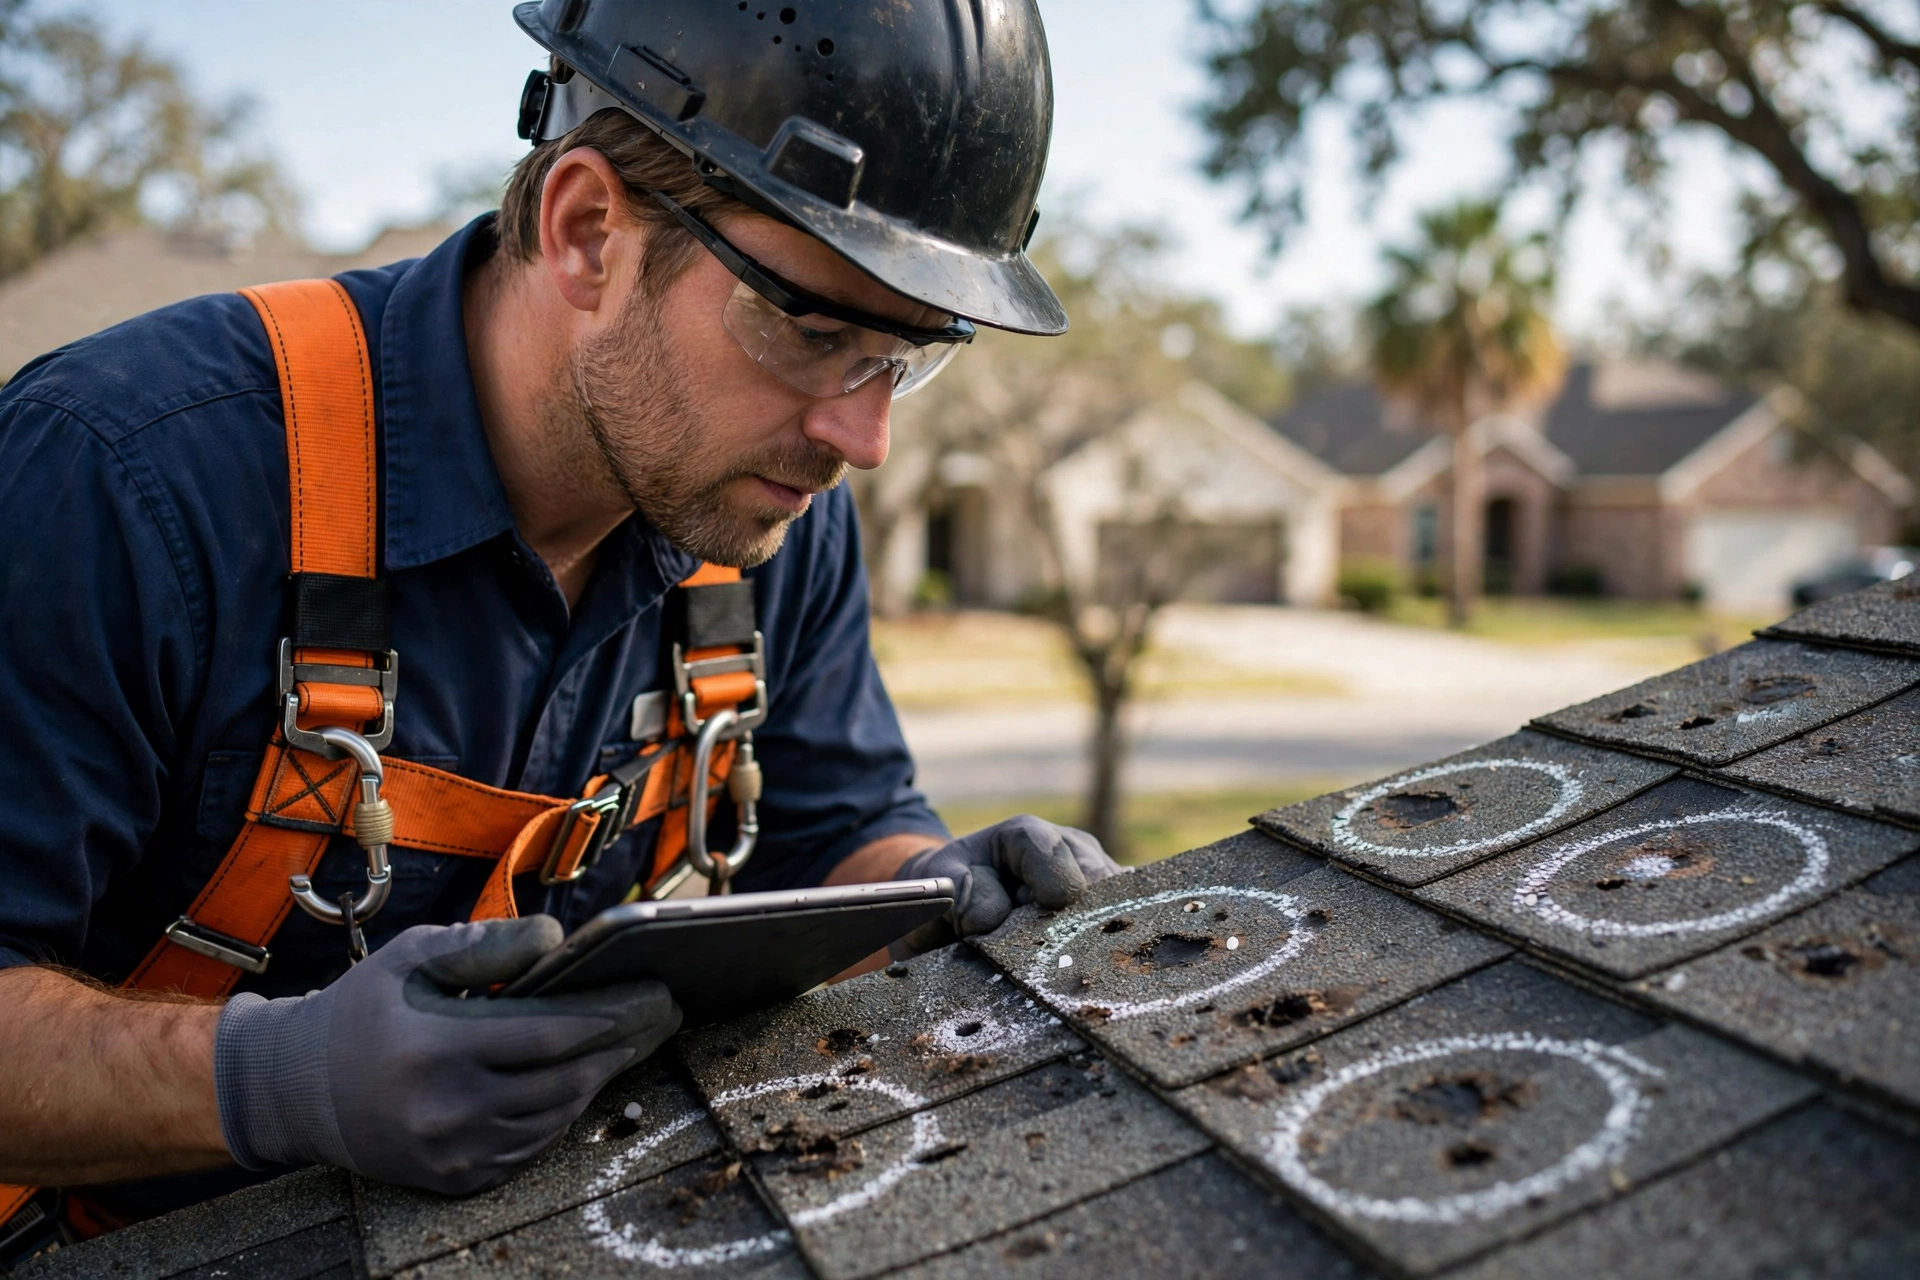
A claim is paid on evidence, so build the strongest file first. Document the storm date with weather data for your address. Photograph every slope, every damaged component — shingles, flashing, valleys, vents, gutters, decking where visible — and every interior consequence, from ceiling stains to damaged belongings. A professional inspection report that marks test areas, counts functional hits per slope, and separates storm damage from wear gives the adjuster a clear, credible map of the loss.
Completeness is the real maximizer. Claims shrink when a damaged slope is never photographed, a torn screen or dented gutter that corroborates the storm is never mentioned, or temporary repair receipts are lost. Keep a single claim folder, log every call with dates and names, and submit requested documents promptly — under Texas Insurance Code Chapter 542, the insurer decision clock of 15 business days runs from when all required documentation has been received, so your speed directly affects your timeline.
Understand Your Policy Before You Negotiate
You cannot claim your full entitlement if you do not know what it is. Determine whether your roof is settled at replacement cost value or actual cash value, whether a roof payment schedule reduces payouts as the roof ages, and whether you carry endorsements that matter — especially ordinance or law coverage, which can help pay for code-required upgrades, and any matching provisions. Calculate your wind and hail deductible in dollars; Texas deductibles are commonly 1% or 2% of the home insured value.
Also learn the payment rhythm: many policies release an initial ACV payment and hold depreciation until completion documentation is submitted. Homeowners who do not know depreciation is recoverable sometimes never claim it, quietly shrinking their own settlement. Ask your agent or adjuster, in writing, exactly what documents trigger each payment stage, then calendar those steps like any other deadline.
- ★Confirm RCV or ACV and any roof payment schedule
- ★Check ordinance or law and matching endorsements
- ★Convert your percentage deductible into exact dollars
- ★Get the depreciation-release requirements in writing
Matching Materials and Full-System Scope
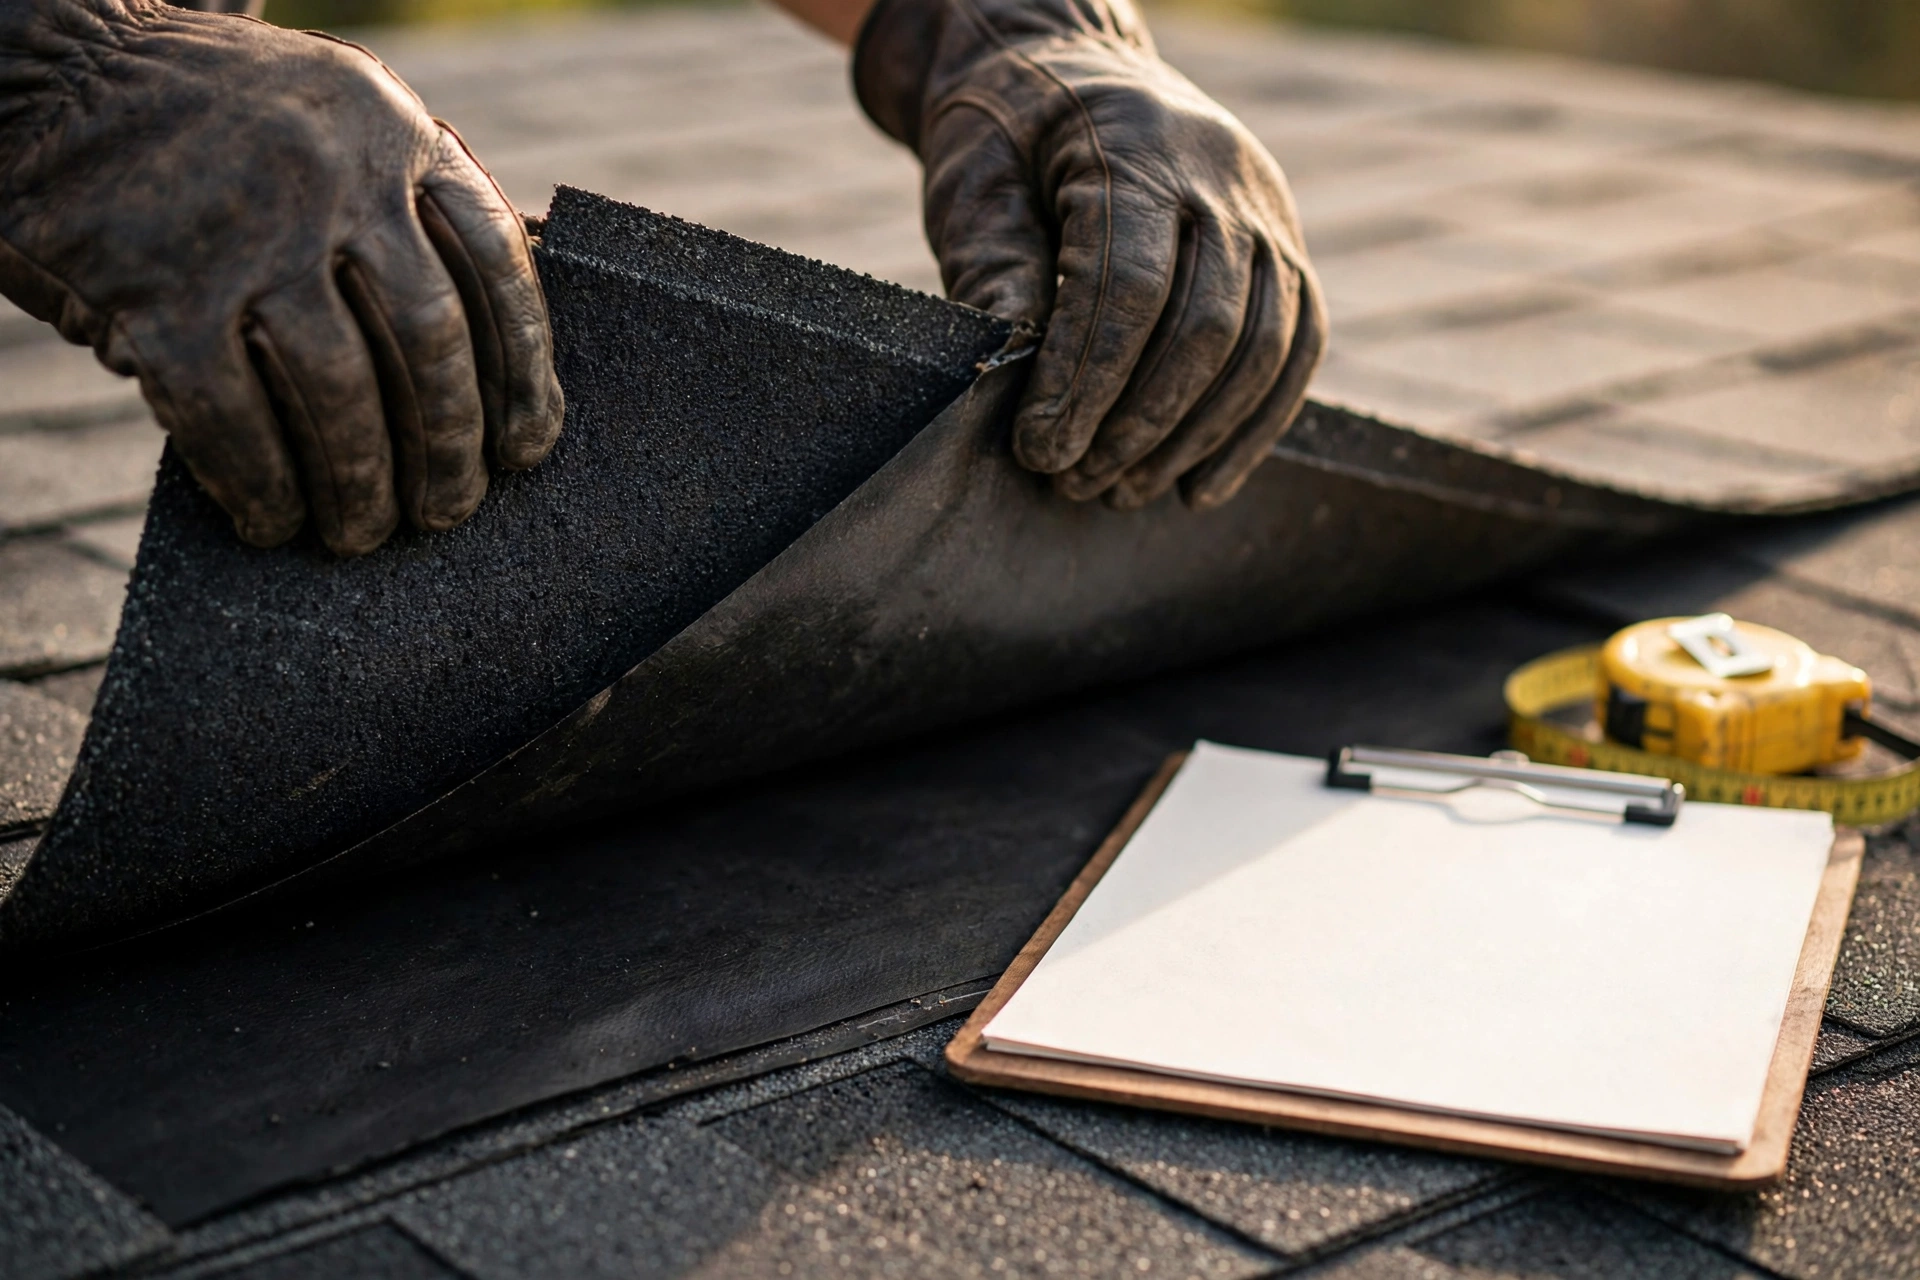
A roof is a system, and legitimate scope includes every component the covered event damaged and every component that must be disturbed to repair it properly: shingles, underlayment, drip edge, flashing, valley metal, pipe boots, and ventilation elements. If damaged shingles are discontinued and no reasonable match exists, policy language and Texas practice around matching become relevant — document the mismatch with samples and manufacturer information rather than simply asserting it, and discuss it factually with the adjuster.
Insist that scope comparisons happen line by line. When the insurer estimate and contractor estimate differ, identify whether the gap is quantity, material grade, or a missing component. Precise, evidenced differences get resolved; vague claims of being underpaid do not. Your goal is a scope that would actually rebuild the roof to its pre-loss condition with like materials, priced completely — that is the definition of a full settlement.
Code Upgrades and Supplements, Done Properly
Texas cities enforce building codes, and a replacement roof must comply with current requirements — drip edge, underlayment standards, ventilation, and decking conditions among them. If your policy includes ordinance or law coverage, code-required upgrades triggered by the covered loss may be payable. The key is proof: cite the specific code requirement, photograph existing conditions during tear-off, and document why the upgrade was necessary for your home, not merely desirable.
Supplements are the legitimate mechanism for items discovered after the initial scope — rotted decking exposed at tear-off, hidden flashing failure, or quantities the adjuster could not see. A proper supplement is a written submission with photos, measurements, code references, and pricing, sent through the insurer process before or as the extra work proceeds. Supplements are not padding; every line should survive the question of what evidence supports it. Contractors who supplement with documentation protect your settlement; those who supplement with pressure endanger it.
The Deductible Law: Your Bright Legal Line
Texas law is plain on this point: it is illegal for a contractor to waive, absorb, or rebate an insurance deductible. The homeowner is required to pay the deductible, and a contractor who pays it, buries it, or inflates an invoice to disguise it is committing an unlawful act — and implicating the homeowner in the arrangement. Any strategy for maximizing your payout that involves your deductible disappearing is not a strategy; it is fraud, and it can void trust, contracts, and coverage conversations alike.
Budget the deductible as a fixed, real cost and maximize everywhere else instead: full documentation, complete scope, code items, and recovered depreciation. That is where legitimate money is found. If a contractor leads with a deductible offer, end the conversation. You have just learned, for free, how that company treats legal obligations when money is involved — believe them.
Red Flags That Shrink or Sink Claims
Certain contractor behaviors actively damage claims. Inflated or invented damage, backdated documents, and pressure to file before an inspection all undermine credibility with adjusters and can trigger investigations that delay legitimate settlements. So can signing an assignment-of-benefits or direction-to-pay document you have not read, which can hand control of your claim — and your payments — to the contractor under terms you never negotiated.
Choose representation the way you would choose any professional: verified local presence, written contract with complete scope and material specifications, milestone-based payments, and a willingness to document everything and explain the process without guaranteeing outcomes no one controls. The strongest claim posture in Texas is boring in the best way — real damage, real evidence, real code, real invoices. Build that, and you will collect everything your policy actually promises.
Not Sure What Your Roof Needs?
Get a photo-documented inspection and decide with evidence.
Questions, Answered
Incomplete documentation and unclaimed recoverable depreciation. Damaged components that were never photographed or listed do not get paid, and many homeowners never submit the completion documents that release held-back depreciation. A complete file and a completion checklist fix both problems.
No. It is illegal in Texas for a contractor to waive, absorb, or rebate an insurance deductible. You are responsible for paying it. Any offer to make it disappear — through side agreements or inflated invoices — is unlawful and a clear sign to choose a different contractor.
A supplement is a documented request to add items to the original claim scope, such as code-required upgrades or hidden damage found during tear-off. It is legitimate when supported by photos, measurements, code citations, and pricing submitted through the insurer process — not when used to pad a claim.